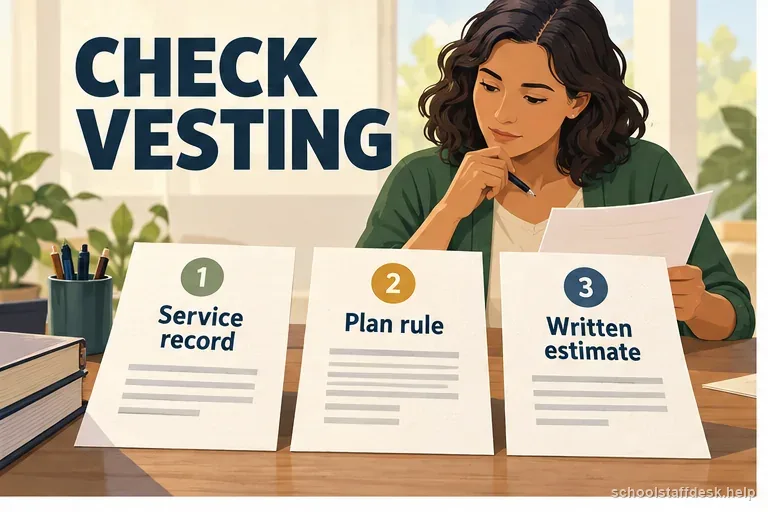
The first question is whether you are vested
Before choosing a refund, find your retirement system’s vesting rule and confirm the service credit posted to your account. If vested, leaving contributions on deposit may preserve a future benefit under the plan. If not vested, the system may still offer a deferred or single-sum benefit, or it may limit your choices; rules differ by tier and service history. Do not infer your options from a national rule or decide from the refund balance alone.
Ask the system for a written or portal estimate of any deferred benefit you could receive at the applicable retirement age. Save the estimate with the date and assumptions.
A refund is not the same thing as taking 'your pension' with you
A defined-benefit refund is not necessarily a portable account containing employer contributions. The refund amount, interest, nonrefundable deductions, and benefits surrendered depend on the plan. For example, Illinois TRS describes a refund based on specified member contributions and says accepting it forfeits TRS benefit rights; other systems set different terms. Ask the plan for both the refund amount and an estimate of the benefits you would give up.
Read the refund form carefully. It should explain what service or future benefit is forfeited and whether the service can later be restored through a redeposit if you return.
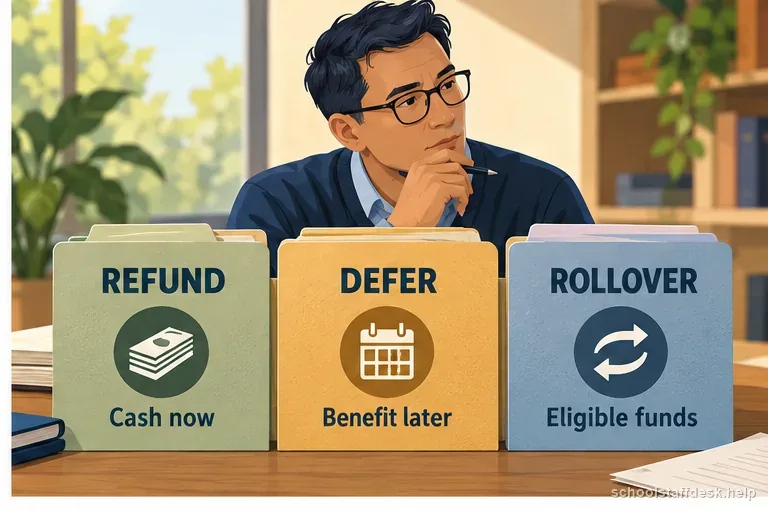
Compare three columns: refund, deferred benefit, eligible rollover
For the refund column, write the cash amount, tax withholding or taxable status, lost service rights, and whether redeposit is possible. For the deferred-benefit column, write the earliest eligibility date, estimated monthly benefit, survivor choices, and whether the account continues earning any plan-defined interest. For the rollover column, confirm what portion is eligible and which destination accounts the plan permits.
Do not use a generic IRA article as the only source. The retirement system controls the distribution, and federal tax rules control the tax treatment.
Do the pension decision in this order: vesting, plan value, tax mechanics, then portability
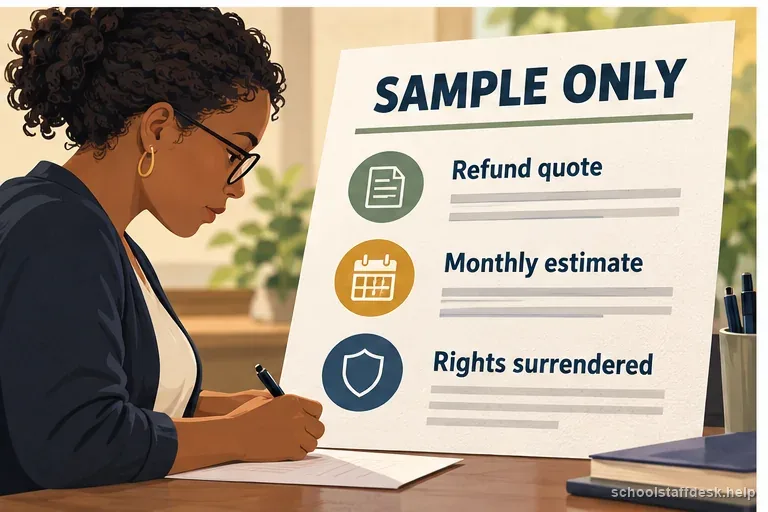
Make a side-by-side comparison from documents issued by the system: the refund quote and forfeiture notice; the deferred-benefit estimate, start date, and payment options; and, if offered, rollover eligibility and receiving-account requirements. Include any nonrefundable deductions and whether service can be restored if you return.
Before a refund, also ask both the old and prospective systems about reciprocity, transfer, or combined-service provisions. These arrangements differ and may not mean that service credit literally moves from one plan to another. Get the effect of a refund in writing before signing.
Do not send a distribution to a new account until its custodian confirms it can receive the specific eligible rollover. Check whether the plan will issue taxable and nontaxable portions separately, whether the receiving account can accept both, and which form the pension system requires. The receiving institution’s verbal assurance is not a substitute for completing the plan’s election form correctly. Keep copies of the election, confirmation, and tax reporting documents with the estimates you used.
Put the choices on one page before you sign. For example, a plan might quote a $32,000 refund and a deferred estimate of $620 per month beginning at age 65. The annual gross estimate is $7,440, so $32,000 equals about 4.3 years of those gross payments after they start. That is only a comparison of the two figures, not a break-even recommendation: it ignores the years until age 65, payment options, inflation adjustments, taxes, survivor benefits, and plan rules. Ask the system to explain those assumptions in writing.
Refund, defer, or rollover decision matrix
| Question | Refund now | Leave for deferred benefit / rollover option |
|---|---|---|
| Vested? | A refund may surrender future plan value; read the plan terms. | Vesting may preserve a future monthly benefit. |
| What money moves? | Confirm employee contributions, interest, and any nonrefundable employer-funded value. | Contributions remain under plan rules until a later distribution/benefit. |
| Tax mechanics | Cash payment can trigger tax/withholding consequences. | An eligible direct rollover may defer current taxation; use plan and IRS instructions. |
| Moving to another public system? | Check reciprocity/transfer before refunding. | Leaving funds may preserve an option that a refund would end. |
| Decision evidence | Get the official refund quote and tax notice. | Get the official deferred-benefit estimate and new-system reciprocity answer. |
Taxes make the form choice matter
A taxable eligible rollover distribution from an employer plan paid to you is generally subject to 20% federal withholding; a direct rollover avoids that mandatory withholding. If you receive an eligible distribution and later roll it over, the IRS generally gives a 60-day window, but eligibility and deadlines have exceptions. A taxable amount not rolled over may be subject to ordinary income tax and, if you are under 59½, an additional 10% tax unless an exception applies. After-tax contributions and state taxes can change the result. Use the plan’s special tax notice and current IRS guidance for your distribution.
If you are considering cash because you need money immediately, compare the after-tax amount you actually receive—not the headline account balance—with the long-term pension or rollover value you are giving up.
A second example shows why the payment route matters. If a $20,000 eligible rollover distribution is paid to you and the taxable portion is subject to the usual 20% withholding, the plan withholds $4,000 and sends $16,000. To roll over the full $20,000 within the applicable 60-day period, you would need to replace the withheld $4,000 from other money. This example assumes the distribution is eligible and fully taxable; your plan notice controls what can be rolled over and how each portion is treated.
Do not use the 20% example as a prediction of your final tax bill. Withholding is a prepayment, and a taxable amount you keep may also affect income tax and, depending on age and exceptions, an additional tax. Ask the plan which amount is eligible, whether any after-tax basis exists, and what forms will report the distribution.
| Example | Inputs and arithmetic | What the math leaves out |
|---|---|---|
| Deferred benefit | $620 × 12 = $7,440 gross per year; $32,000 ÷ $7,440 ≈ 4.3 years after payments begin. | Wait until start age, survivor option, inflation, taxes, and plan terms. |
| Eligible rollover paid to you | $20,000 × 20% = $4,000 withheld; $16,000 reaches you. | A full eligible 60-day rollover may require replacing withholding from other funds. |
Check reciprocity and preserve the written decision before leaving
Once a refund is processed, restoring service can be expensive, require extra service after rehire, or be unavailable under some systems. A rollover can also affect access to funds, investment choices, creditor protections, and survivor provisions. Compare the official plan estimate, IRS tax notice, and receiving-account rules; seek individualized tax or financial advice if the choice is material.
Download your service statement, contribution balance, beneficiary record, refund estimate, deferred-benefit estimate, and any reciprocity guidance. Update your personal email and mailing address with the system. District email may be disabled quickly after separation, while the retirement decision may remain open for months.
If the choice is large relative to your finances or affects retirement eligibility, consider individualized tax or financial advice. This guide can organize the decision but cannot determine which option is best for your household.
Before your last day, save the plan name and tier, your service-credit statement, final pay-period record, vesting determination, and any estimate the system provides. Confirm that the retirement system has a current mailing address and beneficiary designation; deferred members can miss notices if contact details become stale. Ask whether a refund would cancel service credit, health-related retirement eligibility, or a future monthly benefit under that specific plan. Keep the answer in writing and compare the plan's own estimate with any tax professional's explanation before moving money. If you are moving across districts, keep licensing and salary placement separate from a pension refund decision.
- Get the distribution noticeConfirm what the refund includes and what rights or service it ends.
- Ask both retirement systemsCheck reciprocity, transfer, or combined-service options before moving employers.
- Compare tax routesVerify eligible rollover destinations and withholding in the plan notice.
- Save the decision recordsKeep estimates, tax notices, service history, and the answer from each system.
- Confirm service credit and vesting in writing.
- Compare dated refund and deferred-benefit estimates.
- Ask both systems about reciprocity or restoration.
- Confirm eligible destinations and tax treatment.
- Save the notice, signed election, and receipt.
| Document | What it confirms | Question to resolve |
|---|---|---|
| Service statement | Posted years, tier, and contribution history. | Is the service record complete and vested? |
| Deferred estimate | Start date, gross amount, and payment assumptions. | What future benefit stays if funds remain? |
| Refund notice | Eligible cash, forfeitures, and restoration rules. | What plan rights end if you accept it? |
| Tax notice | Eligible rollover portions and withholding. | Which destinations accept each portion? |
Mistakes to avoid before the election becomes final
Common costly mistakes include treating the refund quote as the whole pension value, assuming employer contributions are included, and sending money to an account before its custodian confirms it can accept the exact rollover. Another is refunding before asking a new public retirement system about reciprocity or service restoration. These are plan questions, so get the answer from both systems and keep the response with the estimates.
Pause before signing if the notice does not explain which service credit or future benefit ends, if the estimate uses a different retirement age than you expect, or if a deadline or tax classification is unclear. A tax professional can review a distribution with unusual after-tax amounts, multiple eligible plans, or a deadline concern. A qualified financial or tax adviser can help compare household-specific consequences; the plan administrator remains the source for plan eligibility and benefit calculations.
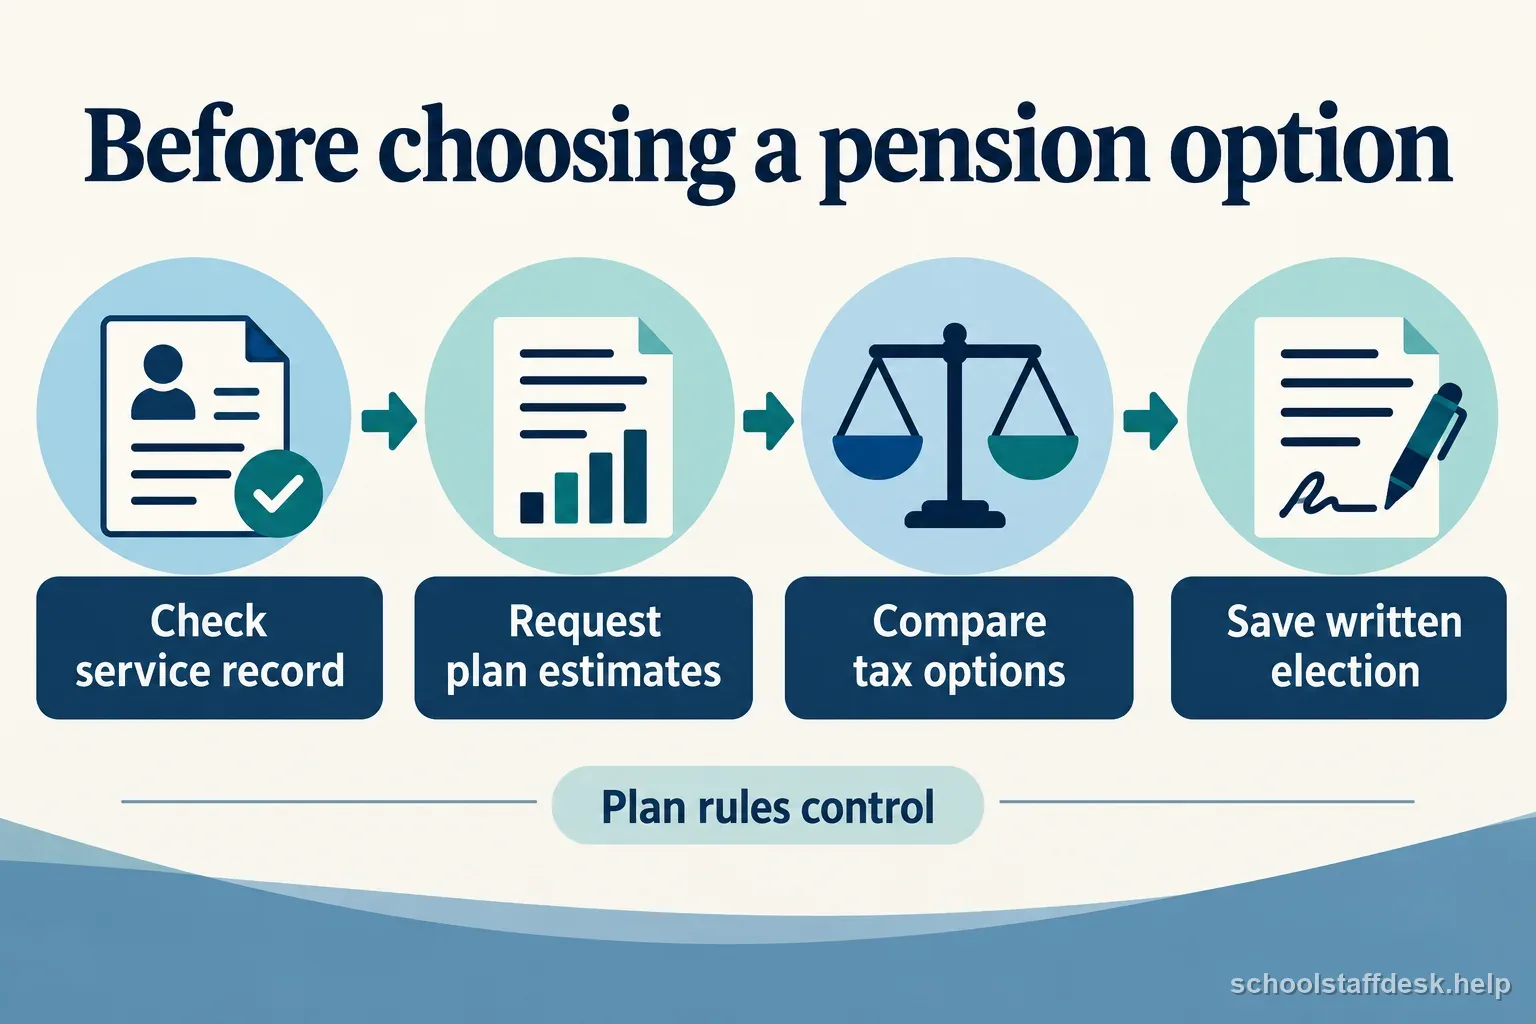
Use this ordered checklist: confirm the posted service history and vesting decision; request dated refund and deferred-benefit estimates; ask about reciprocity or restoration before a refund; have the receiving account confirm eligible rollover types; read the plan tax notice; then save the signed election and confirmation. Do not submit an irreversible election just to meet a district separation date without asking the retirement system how long the option remains open.
Sources used for this guide
- Illinois TRS — Refund of Retirement Contributions
- Teacher Retirement System of Texas — Refunding Your Member Account
- Internal Revenue Service — Rollovers of retirement plan and IRA distributions
- U.S. Department of Labor — What You Should Know About Your Retirement Plan
Rules can change. Use these sources as a starting point and confirm any state, district, student-plan, employment, licensing, or retirement requirement with the agency or team that governs your situation.
Questions school staff ask about this situation
What does vesting change when I leave teaching?
Vesting can determine whether you retain a right to a future monthly pension if you leave contributions in the system. The required service and benefit rules vary by system and tier.
Do I get employer pension contributions back if I take a refund?
Do not assume so. Defined-benefit refund rules are plan-specific, and the employer-funded value of the pension generally is not simply a portable account balance. Check the system’s refund terms.
Is a direct rollover the same as taking cash?
No. Federal tax and withholding treatment can differ. Use the retirement system’s distribution notice and current IRS rollover guidance before choosing the payment method.
Should I take a refund before moving to another public employer?
Check reciprocity, combined-service, or restoration rules first. A refund can sometimes eliminate service relationships that would have been valuable in the new public system.